Moody’s sees Chilean companies under 2027 cash-flow pressure as copper capex rises
Falling ore grades, longer haul distances and water infrastructure are adding to the spending burden across Chile’s copper mines.
Why it matters: Chile’s copper producers must fund resource replacement and water and energy infrastructure while lower ore grades make production more demanding.
US$111,149 million — projected Chilean mining investment for 2026–2035.
72 projects — initiatives included in the latest national investment portfolio.
84.5% — copper’s share of projected mining investment.
US$51,544 million — investment planned for the Antofagasta region.
Moody’s expects high investment to keep free cash flow under pressure at several Chilean companies in 2027, but says available liquidity and access to financing should limit near-term refinancing risks. Copper miners face a more supportive credit environment than some other sectors, backed by international metal prices, even as operating and capital costs weigh on the cash they retain.
Investment needs will test cash generation
The pressure stems from the gap between cash generated by operations and the capital needed to maintain or expand production. Negative free cash flow does not necessarily signal insolvency: companies may continue to operate profitably while spending more than they generate on projects, drawing on cash reserves or financing to cover the difference.
Moody’s expects Latin American non-financial companies’ credit quality to remain broadly stable in 2027, but with a negative bias. Chile, Mexico and Peru are relatively stable in its regional outlook, while Brazil and Colombia face greater difficulties and Argentina shows signs of recovery. Within Chile, forestry companies face tighter financial constraints than copper miners. Moody’s points to investment cycles at Celulosa Arauco y Constitución and a potential large-scale project at Inversiones CMPC. CMPC sold assets for about US$1,000 million during 2026 to strengthen its financial position ahead of further investment decisions.
Companies with solid balance sheets and access to capital markets are better placed to manage negative cash flow than those with high leverage or debt maturities that require refinancing under less favourable conditions.
Copper prices meet rising production demands
Copper’s demand outlook is supported by electrification, energy infrastructure and technology development. But lower grades mean mines may have to process more material to recover an equivalent amount of metal, depending on geological and metallurgical conditions. Ageing deposits and longer internal haul distances add to operational demands, while processing more material can increase energy use, equipment requirements and investment in plant capacity.
Water is another major capital requirement in Chile’s northern mining regions. Desalination plants, seawater pumping systems and supply networks can support operations but also require substantial investment. Climate variability adds uncertainty around water availability, infrastructure and operational continuity. As a result, stronger copper prices do not automatically translate into more cash after capital spending.
Artificial intelligence could support longer-term copper demand through investment in data centres, storage and electricity networks, which use the metal in conductors, transformers and other equipment. Its near-term effect on individual miners’ finances is indirect, however, and depends on prices, production costs and companies’ ability to increase supply.
Antofagasta accounts for a large share of planned projects
Chile’s 2026–2035 mining investment portfolio totals US$111,149 million, up 6.3% from US$104,549 million in the previous period, and includes 72 projects, compared with 59 previously. Lithium investment rose from US$4,700 million to US$10,800 million, while copper remains the largest component. These are projected investments, not committed spending; permits, financing, commercial conditions and final company decisions will determine which projects proceed.
Antofagasta accounts for US$51,544 million, or about 46% of the national total, including US$44,994 million in copper-related initiatives. The projects include BHP’s US$1,300 million Escondida Leach Pad B1 Extension, intended to sustain annual cathode production of 210,000 tonnes, and Capstone Copper’s US$500 million Mantos Blancos Capacity Improvement project. The latter is designed to extend operations to 2041 and lift sulphide extraction to 9.8 million tonnes a year.
For investors, the key measures in 2027 will include operating costs, capital expenditure, debt maturities and how companies finance projects without unduly weakening their balance sheets. The Central Bank of Chile’s latest Financial Stability Report describes a less favourable economic environment for companies and households, while assessing the banking system as sufficiently solvent to sustain financing under stress. The execution of the proposed mining investments will depend on project approvals, financing and final investment decisions.
More in Resources
Copper drops to US$5.54/lb as London inventories rise and losses extend
The nine-session slide has pushed Chile’s benchmark export below its 2026 average as traders reassess industrial-demand signals.
Sernageomin reviews safety systems at Pucobre and Candelaria in Atacama
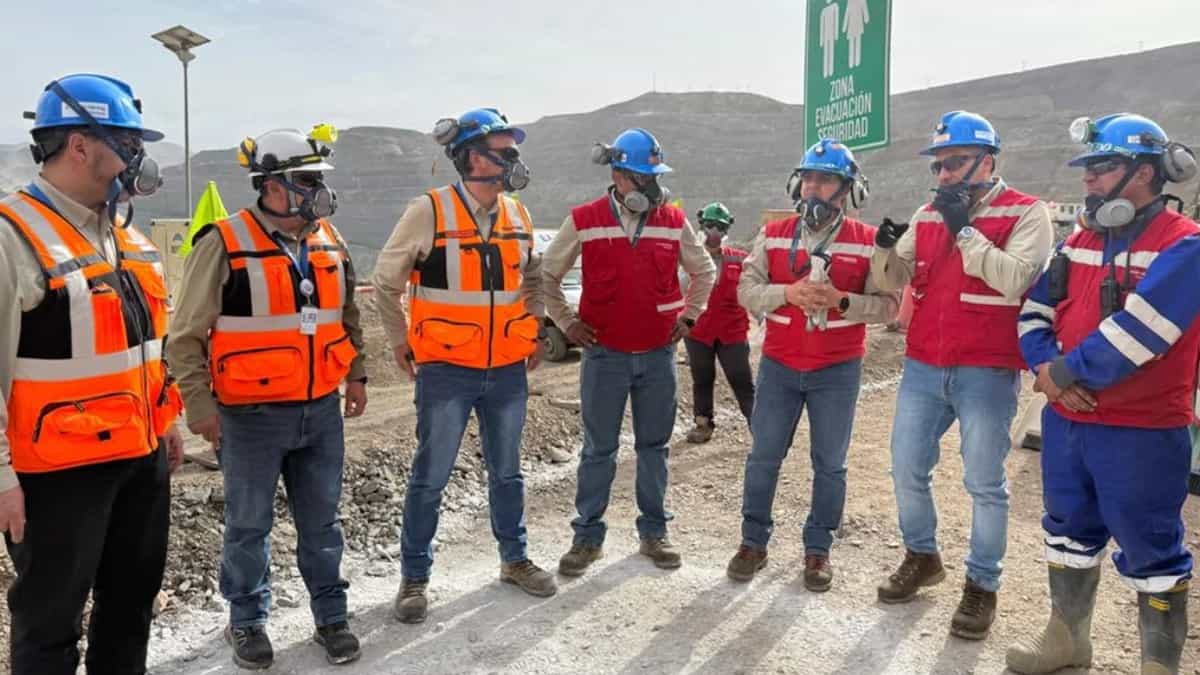
One operation was underground and the other an open pit, putting emergency readiness and operational controls under different tests.
Chile’s O’Higgins 220 kV line faces a connection deadlock after workaround rejected
The line is built, but its planned tie-ins depend on substation works delayed by failed tenders.