Endeavour Silver's Pitarrilla study prices a US$585M build before key permit
The 18-year underground model uses US$50 silver, but its returns change materially across the study's sensitivity cases.
Why it matters: Pitarrilla could become a long-life polymetallic operation, but its capital requirements and outstanding tailings approval remain central to any construction decision.
US$736 million — after-tax net present value at a 5% discount rate
US$585 million — estimated initial capital, before sustaining investment
18 years — planned mine life, with average annual production of 7.5 million ounces AgEq
US$50 per ounce — silver price used in the base case
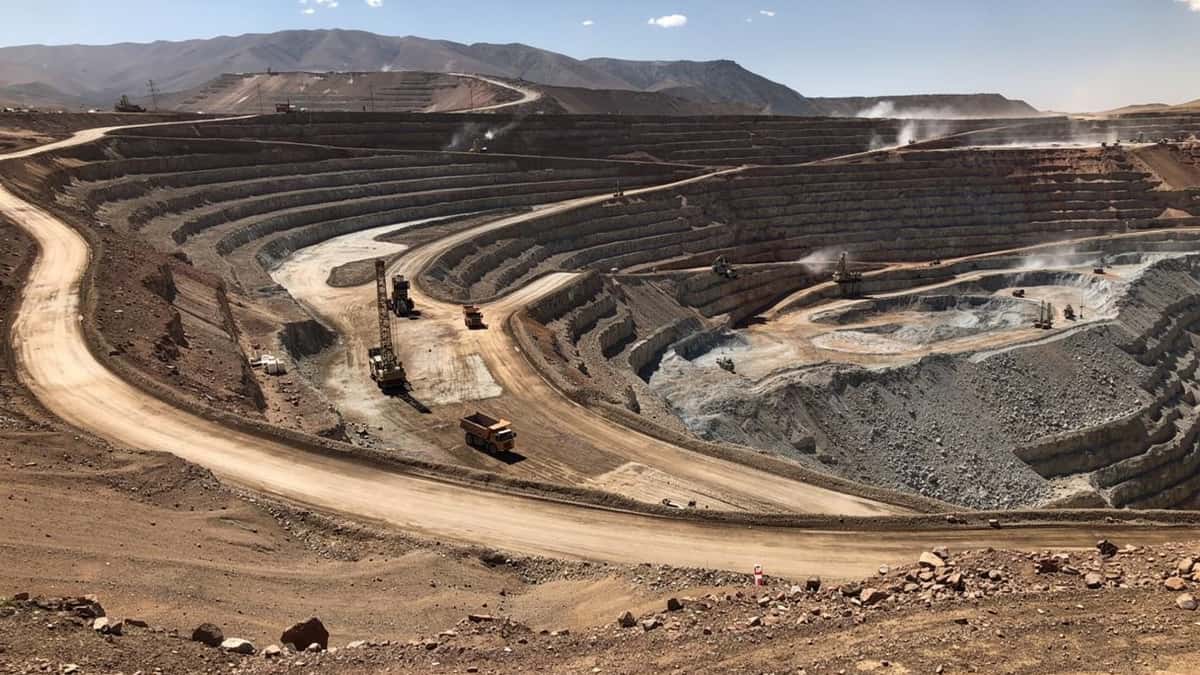
Endeavour Silver's feasibility study for the Pitarrilla project in Durango, Mexico, estimates an after-tax net present value of US$736 million and an initial investment of US$585 million. The underground mine is designed for an 18-year operating life, but the permit for its tailings storage facility remains pending. The study does not represent a construction decision by the company.
The base case uses a silver price of US$50 per ounce, alongside lead at US$2,028.23 per tonne and zinc at US$2,733.70 per tonne. At those assumptions, the after-tax internal rate of return is 16.37%. The company estimates US$1.712 billion in free cash flow after capital investment and a five-year after-tax payback period.
Pitarrilla's output and price sensitivity
The mine plan calls for a mechanised underground operation extracting sulphide ore, mainly through longhole stoping and in-ore development. The processing plant has a design capacity of 4,000 tonnes per day; the life-of-mine average is 3,817 tonnes per day.
Over the mine life, the study forecasts processing 25.1 million tonnes and producing 97.8 million ounces of silver, 231,046 tonnes of lead and 518,900 tonnes of zinc. Total production is estimated at 135.5 million ounces of silver equivalent (AgEq), with silver expected to contribute 73% of revenue. Average annual output is projected at 7.5 million ounces AgEq over the full mine life, rising to 7.9 million ounces in the first five years of full production.
The economic case is sensitive to silver prices. At US$30 per ounce, the study estimates an after-tax NPV of US$109 million and an IRR of 7%. At US$60 per ounce, those figures rise to US$1.049 billion and 20.32%. The study places the silver break-even price below US$30 per ounce, while noting that results also depend on its price and cost assumptions.
Capital, costs and processing design
The study estimates another US$119 million in sustaining capital, bringing total capital costs to US$704 million. Construction is forecast to take 30 months. Average direct costs are estimated at US$109.24 per tonne processed; after by-product credits, life-of-mine cash costs are US$12.66 per payable ounce of silver and all-in sustaining costs are US$15.06 per ounce. Forecast lifetime revenue totals US$6.051 billion, including US$4.433 billion from silver.
The processing circuit would use crushing, grinding and flotation to produce lead-silver and zinc-silver concentrates. Filtered tailings would be placed in a dry-stack facility. Mine development totals about 16.7 kilometres, including 5.4 kilometres in the initial phase, and the plan includes stockpiling more than 600,000 tonnes of ore during construction.
Tailings approval remains outstanding
Pitarrilla covers about 4,950 hectares across five concessions in the municipalities of El Oro and Indé. The project has permits for water use and discharge, explosives, land-use change, development and underground mining, according to Endeavour. The tailings storage facility permit and other approvals or amendments remain outstanding.
The planned access route includes about 47 kilometres of existing roads and a permanent bridge over the Nazas River, roughly 11 kilometres from the property. Endeavour said it would file a supporting technical report on SEDAR+ within 45 days of announcing the study, under NI 43-101. The company acquired Pitarrilla from SSR Mining in 2022 for US$70 million in cash and shares, plus a 1.25% net smelter return royalty; the study's construction case remains subject to the outstanding approvals and a separate company decision.
More in Resources
Chile orders Alcaparrosa closure, but the 2022 collapse is only part of the case
The mine had been suspended since July 2022, but the court's findings reach into the Copiapó River aquifer and Tierra Amarilla.
Tintina starts 40,000m at Dos Amigos, but feasibility needs more than drilling
A move straight from preliminary assessment to feasibility puts resource classification, engineering and permitting on overlapping schedules.
Chile’s geothermal power potential faces a hurdle beyond its reservoirs
Cerro Pabellón was still the country’s only geothermal plant in October 2022, despite estimates pointing to a far larger role for the resource.